Jensen’s Inequality
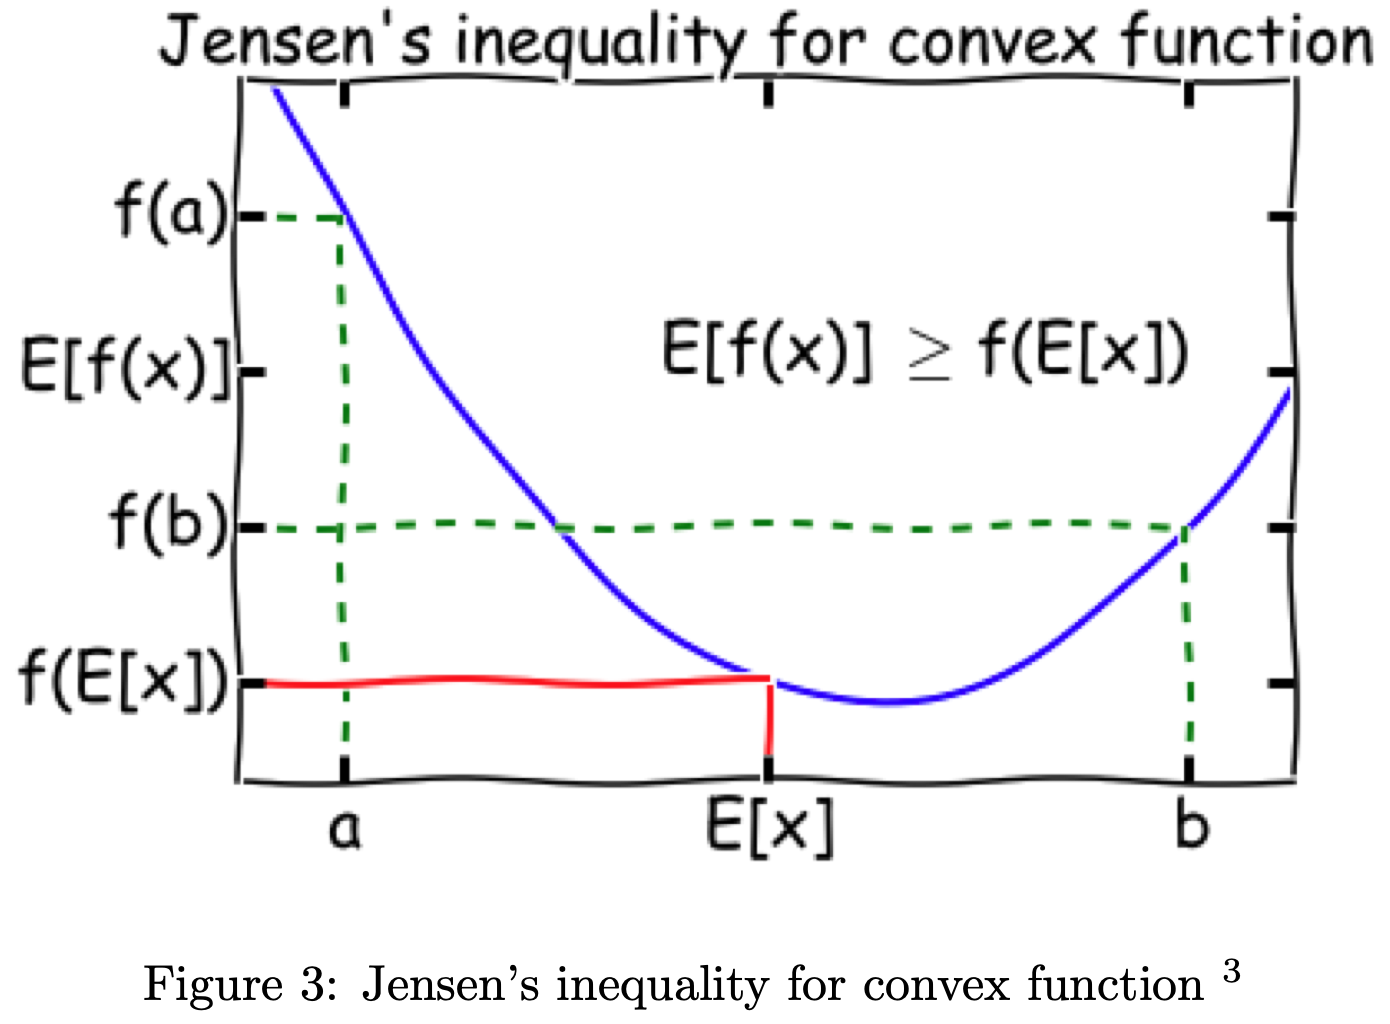
For a random variable , if is convec (refer. convex function), then .
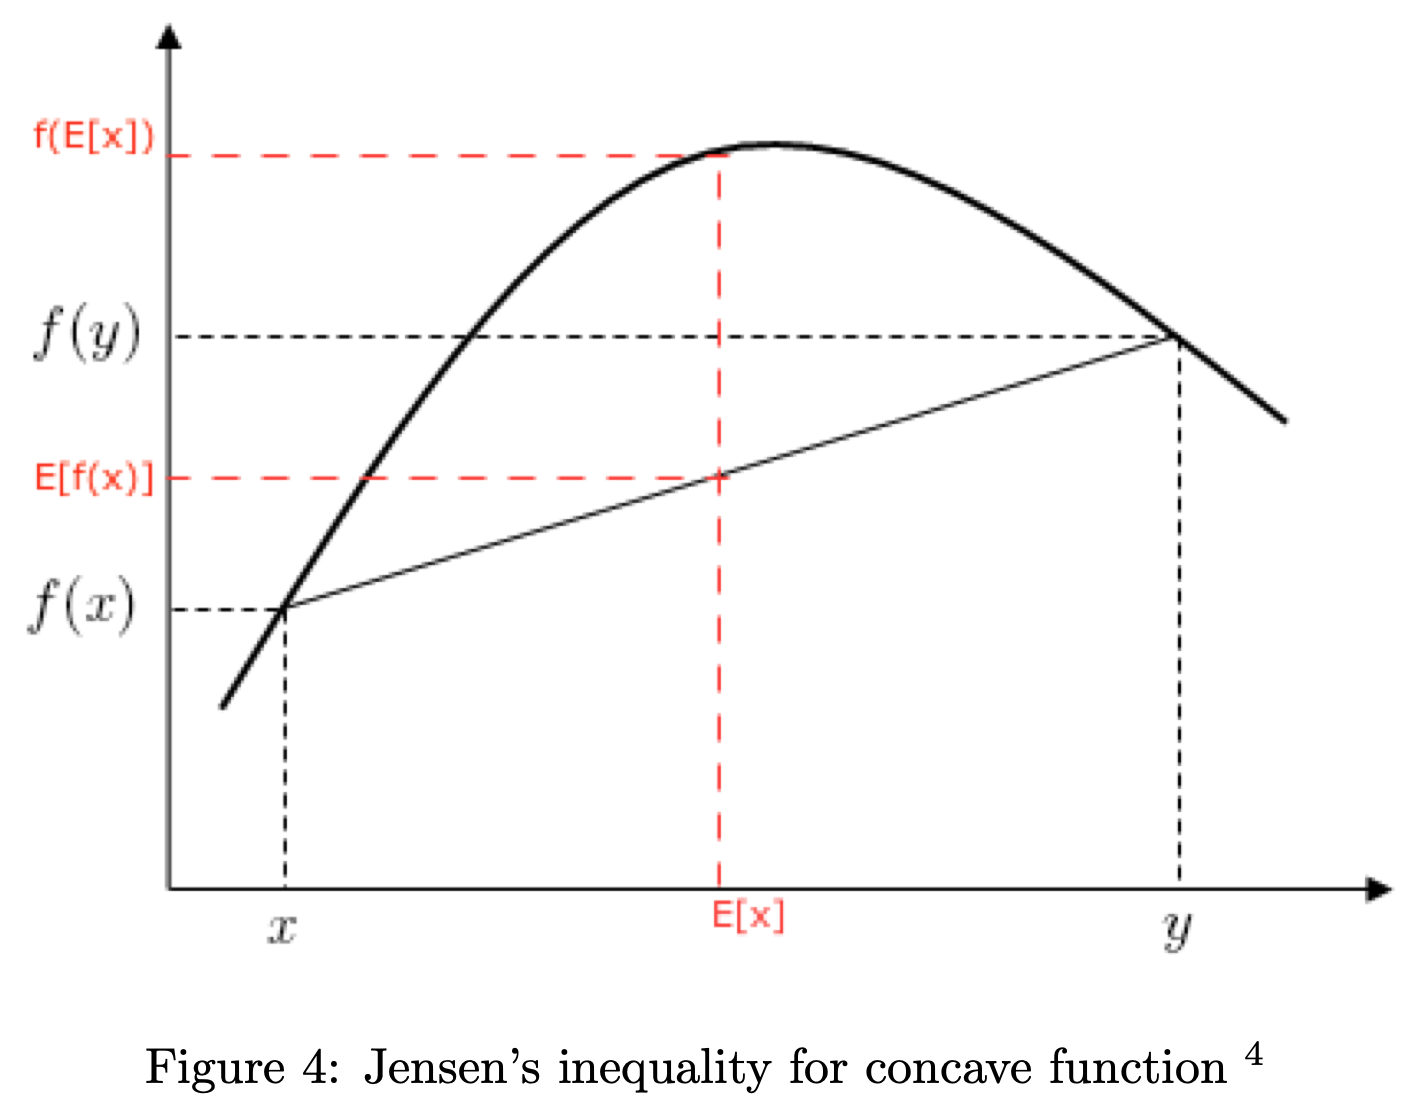
For a random variable , if is concave, then
(위와 반대).
Note
- Jensen 의 부등식에서 등호가 성립하는 경우는 다음과 같습니다: 이 성립하려면, 가 상수일 때만 가능합니다.
For a random variable x, if f(x) is convec (refer. convex function), then E[f(x)]>=f(E[x]).
For a random variable x, if f(x) is concave, then f(E[x])>=E[f(x)]
(위와 반대).
Convex ? Concave f(x) is concave, iff -f(x) is convex. Convex Quadratic Function 아래 그림과 같이 오직 하나의 minima (global minimum) 밖에 존재하지 않는 비용 함수 J 를 convex quadratic function 이라 부른다. convex 는 윤곽이 볼록하다는 뜻이다. Strictly Convex Fun...
EM Algorithm 으로 풀 수 있는 문제들 mixture gaussian problem, Probabilistic latent Semantic Indexing, K-means 정의 EM algorithm is an iterative method and a bound optimization algorithm to find (local) MLE or MAP estimates of param...
한줄 요약 KL-Divergence(Kullback-Leibler Divergence)는 두 확률분포가 얼마나 다른지를 재는 값이다. 직관으로는 “진짜 분포가 P인데 내가 Q라고 믿고 행동하면, 평균적으로 얼마나 손해를 보나” 를 잰다. 정보이론 관점에서 그 손해는 “낭비되는 비트 수”이고, 통계 관점에서는 “잘못된 모델이 데이터를 얼마나 덜 그럴듯하게 보나”다. 핵심 성질 세 가지만 기억하...
f(x) is convex, iff f^{\prime\prime}(x)\geqslant0,\forall\mathrm{x}\in R f(x) is strictly convex, iff f^{\prime\prime}(x)>0,\forall\mathrm{x}\in R f(x) is concave, iff -f(x) is convex.
최적화 문제 (Optimization problems) 란 여러개의 선택가능한 후보 중에서 최적의 해 (Optimal value) 또는 최적의 해에 근접한 값을 찾는 문제를 일컫는다.
간단한 모델에서는 p\left(z\mid x;\theta\right) 에 대한 analytical solution 이 존재하여 q(z)=p\left(z\mid x;\theta\right) 을 구하는 것이 tractable 했다. 대신, x 가 주어졌을 때, latent variables 의 집합이 나머지 latent variables 에 대하여 독립임을 가정하면...
tight lowerbound LL(\boldsymbol{\theta}) ,
Method of finding a local maximum subject to constraints. Maximize f(x,y) and subject to g(x,y)=c (constraint) Assuming that f and g have continuous partial derivatives. Lagrange...
Global minimum 은 목적 함수 전체 영역에서 가장 작은 값을 가지는 지점이다.
Newton’s method 라고 불리기도 하며, 실수 함수의 approximate 한 해를 빠르게 찾는 방법이다. Newton-Raphson method 는 f(x) 의 해를 찾기 위해 다음을 무한히 반복한다
Newton-Raphson method 대신 사용하는 방식으로, 주어진 함수들에 대한 로컬 maxima 또는 minima 를 찾는 방법이다.
bias correction 은 지수이동평균을 구할 때, 처음에 평균에 발생한 bias 부분을 고쳐주는 역할을 하는 방법이다.
variational inference 와 동일한 아이디어를 채택한 방식이다. 즉, posterior density 인 p(\theta \mid x) 를 g(\theta \mid \phi) 라는 density 로 근사시키는데, 이때 factorize 되는 형태를 취하게 한다.